How Rising Interest Rates Impact Consumer Borrowing in the Lending Industry
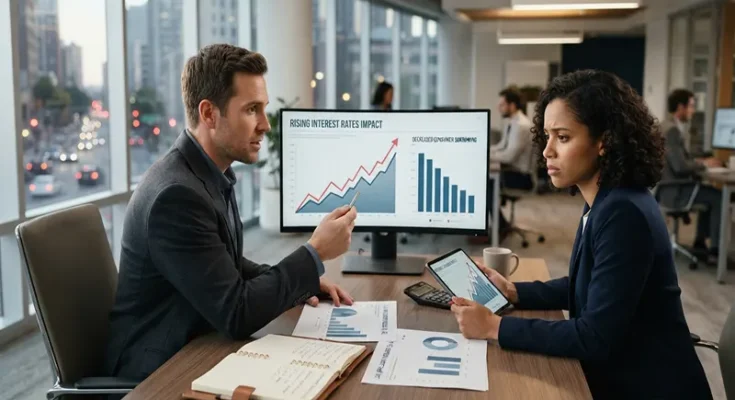
When central banks enact monetary tightening and raise benchmark interest rates, the macroeconomic landscape shifts overnight. An era characterized by cheap, abundant capital rapidly gives way to an environment of expensive, selective credit.
For the lending industry, these shifts act as a powerful economic brake. Rising interest rates fundamentally reshape consumer borrowing behavior, tighten underwriting standards across financial institutions, and force both lenders and borrowers to adapt to a vastly different financial reality.
The Direct Mechanics: How Rate Hikes Cascade to Consumers
To understand how high-rate environments affect everyday consumers, you must look at how benchmark rates cascade through the financial system. When central banks raise the federal funds rate, commercial banks immediately raise their prime rates—the baseline index used to price consumer credit products.
The impact hits different types of debt in distinct ways:
- Variable-Rate Debt: Credit cards, home equity lines of credit (HELOCs), and adjustable-rate mortgages (ARMs) experience